


High-yield bonds defy doom in crisis after crisis
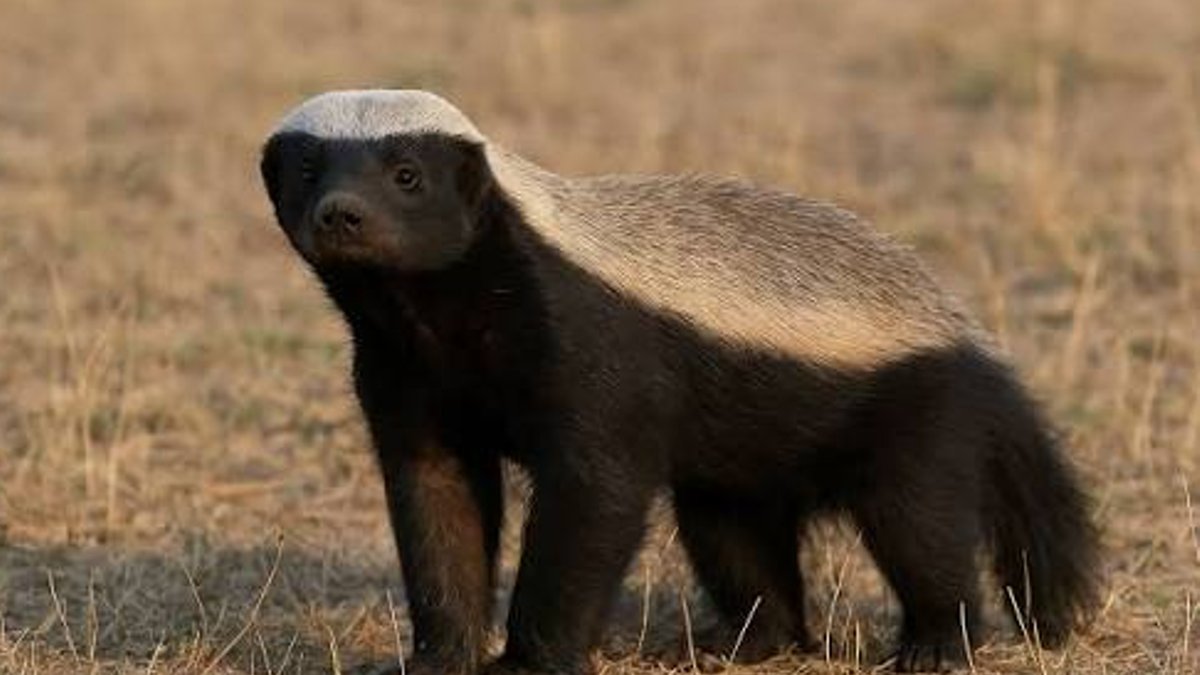
A decade of financial turbulence has cemented the US high-yield bond market’s reputation for endurance—one now tied to an unexpected symbol: the honey badger. The meme-era creature, infamous for battling lions, venomous snakes, and swarms of bees, mirrors how high-yield spreads have endured repeated crises. Oil price collapses, Federal Reserve tightening cycles, pandemics, wars, inflation surges, and recession warnings have all forced spreads to widen. Yet the market has consistently rebounded, often more quickly than analysts projected. The comparison is imperfect—high-yield bonds do respond to disruptions—but the pattern is undeniable: none of these events sparked the widespread credit unraveling that investors initially feared.
Consider 2022, when economists and financial models universally predicted a recession. It failed to materialize. Corporate profits outperformed forecasts, and default rates stayed below expectations. A similar dynamic emerged after the 2020 pandemic sell-off, when unprecedented fiscal and monetary stimulus prevented a surge in defaults. Even the Ukraine war, which initially caused spreads to spike sharply, saw a rapid recovery as geopolitical risks failed to translate into lasting credit stress across the broader market.
The market’s resilience stems partly from structural changes. In 2007, bonds rated BB, the higher-quality segment of high yield, comprised roughly 38% of the US High Yield Index. By 2026, that share had climbed to 60%. Over the same period, bond maturities shortened, secured debt issuance expanded, and refinancing overtook acquisition financing as the primary use of proceeds. The index now includes a greater proportion of safer borrowers, while private credit and leveraged loans have absorbed much of the riskier debt. This shift has improved the overall risk profile of the market, even as funding gaps have begun to appear in private credit sectors.
Private credit struggles reshape risk exposure
Private credit funds have faced notable stress in recent months, particularly in portfolios heavily exposed to technology sectors. Some issuers that previously depended exclusively on loans are now returning to high-yield bonds, signaling liquidity challenges in private markets. However, these adjustments have not yet weakened the index’s fundamental quality. The reallocation of risk appears contained, with analysts noting that private credit’s struggles remain concentrated in specific segments rather than spreading systemically.
Technical factors have also reinforced the market’s stability. New bond issuance has remained subdued in recent years, partly because strong demand for loans and private credit absorbed much of the riskier debt. Meanwhile, investor appetite for yield has stayed robust, creating an imbalance that has helped keep spreads tighter than historical norms. Higher base rates have further supported total returns, making high-yield bonds more attractive even as spreads narrow. The combination of limited supply, strong demand, and raised borrowing costs has created a self-reinforcing dynamic where volatility tends to correct itself rather than escalate.
Two exceptions stand out: the energy sector and the pandemic recovery. Energy historically dominated the index during past crises, distorting its overall behavior. When energy is excluded, spreads have recovered even more swiftly. The pandemic’s rebound, by contrast, relied more on policy interventions than corporate fundamentals. Massive stimulus packages prevented a default wave, though those same measures later contributed to inflationary pressures. These episodes highlight how external factors can temporarily override market mechanics.
Higher rates test resilience of recovery cycles
The honey badger analogy holds because the market does not ignore shocks. Spreads widen in response to rising risks, and investors reassess valuations accordingly. The critical distinction is that these reactions rarely escalate into full-blown credit crises. The open question is whether this resilience can endure in an environment of persistently higher interest rates, where borrowing costs may strain corporate earnings and refinancing needs arise. The next disruption, whether driven by sustained oil prices, fresh geopolitical tensions, or an unforeseen economic development, remains unpredictable.
That said, it is important to distinguish between different segments of the private credit market. Much of the recent stress has been concentrated in parts of the US private credit universe, where some loan and private credit funds have recently been burned by the lower-quality composition of their portfolios. They have also been singed by issuer concentration, particularly during the recent sell-off in certain technology-related issuers, as those asset classes are disproportionately skewed towards technology relative to high yield.
Interestingly, amid the recent revival of issuance, an increasing number of previously loan-only issuers have been approaching the high yield market, perhaps a sign that funding options in US loans and private credit are becoming less abundant as some funds either come under pressure or lack the capacity to continue funding weaker issuers.
The technical foundations of the market’s endurance are equally significant. This supply-demand imbalance has kept spreads narrower than historical averages, even as base rates rose. Investors, seeking yield in a higher-rate world, have shown little hesitation to enter the market when spreads widen, provided the total yield remains attractive. The interplay of these factors, constrained supply, persistent demand, and raised borrowing costs, has created a cycle where market corrections tend to be self-contained rather than spiraling.
Honey badger myth: Limits to market endurance
However, the honey badger analogy has its limits. The creature’s fearlessness comes with a high mortality rate; similarly, the high-yield market’s ability to recover from shocks does not guarantee immunity to long-term damage. The current environment, with the 10-year Treasury yield near 5%, tests whether the market’s resilience can withstand sustained higher borrowing costs. Issuers with maturing debt or limited cash reserves may struggle to refinance, especially if revenue growth stagnates. The uncertainty lies not in whether the next shock will arrive, but in whether it will reveal vulnerabilities even the most adaptable market cannot overcome.


